By Patrick Foley, Business Owner
Storm Damage and Home Insurance in Munster at a Glance
- Home buildings insurance in Ireland normally covers sudden damage caused by a storm, including gutters, fascia and roof. Insurance Ireland says household buildings and contents policies cover storm damage.
- It normally does not cover gradual wear, rot or poor maintenance. If a gutter was already rusted through or a slate was already loose, the insurer may say the storm was not the cause.
- Cover depends on your own policy. Excesses, the wording of "storm" and the notification rules differ between insurers, so check your policy schedule or ring your insurer.
- Photograph the damage before anything is moved, make it safe, keep every receipt, and tell your insurer promptly.
- Munster Gutters gives you the dated photos, a written report and a costing in the form insurers ask for, and deals with the loss adjuster for you. Call 021 7020328 (Cork), 061 535761 (Limerick), 066 4004809 (Kerry) or 051 263717 (Waterford).
Is storm damage covered by home insurance in Ireland?
Usually yes, if the policy includes buildings cover and the damage was sudden. Insurance Ireland, the industry body, states that household buildings and contents policies cover damage caused by storms. In practice this includes slates and tiles blown off, ridge tiles lifted, gutters and downpipes pulled from the wall, fascia and soffit boards torn away, and rain getting into the house through a storm-damaged roof.
Two things sit outside most policies. The first is gradual deterioration: rust, rot, old nails giving way, blocked gutters that overflowed. The second is anything your policy excludes by name. Wording differs. Allianz Ireland, for example, describes its storm cover as wind of more than 47 knots (87 km/h), while another insurer may define it differently. We cannot tell you your insurer's definition. Your policy schedule can.
What storm damage to gutters and roofs looks like
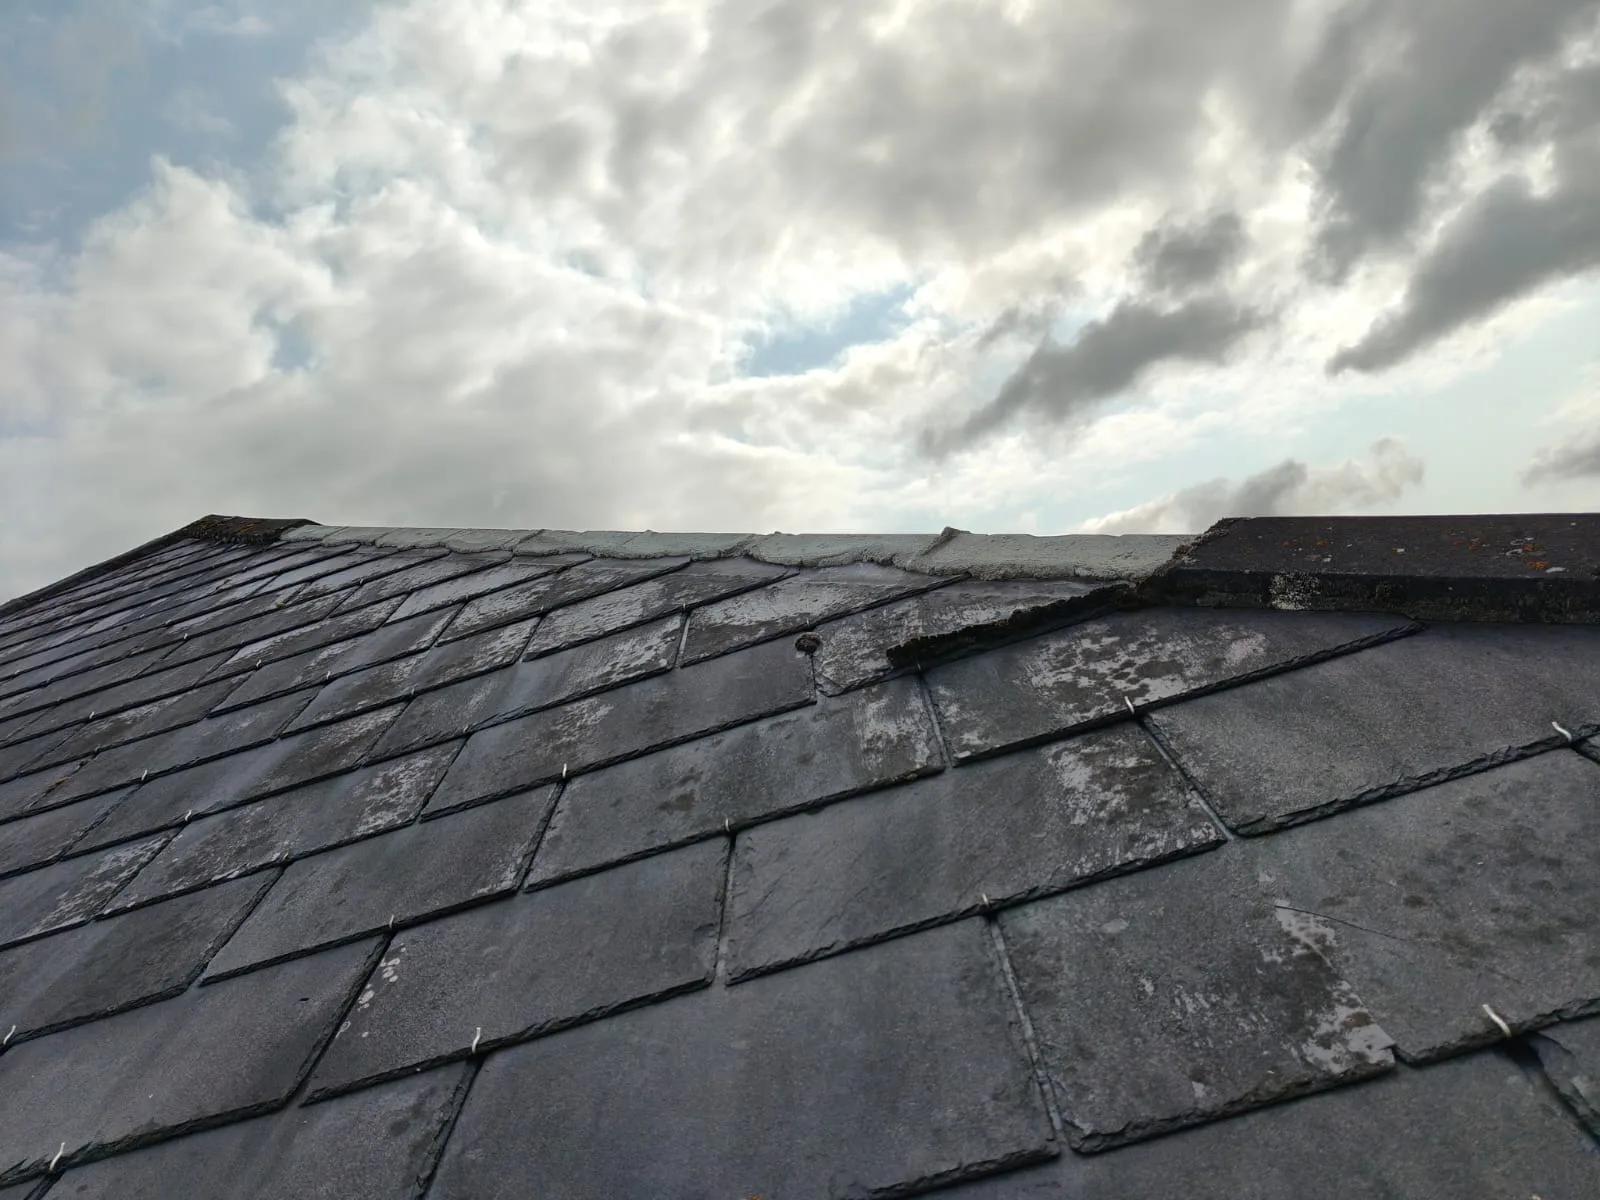
- Gutters sagging, pulled away from the fascia or lying on the ground
- Downpipes snapped or bent
- Slipped, cracked or missing slates and tiles
- Lifted or cracked ridge tiles
- Lead flashing peeled back around chimneys
- Fascia and soffit boards split or loose
- A damp patch or drip inside that was not there before the storm
A leak can show up days after the wind has dropped, so check the attic and ceilings as well as the outside.
Does insurance cover old or worn gutters?
Not if the insurer decides wear caused the failure. Insurers send a surveyor or loss adjuster to decide what caused the damage. If the same storm damaged a well-kept gutter, that is a storm claim. If the gutter was rotten and the wind finished it off, the insurer may refuse. This is why photographs of the damage, and of the condition before it where you have them, matter so much. Regular gutter cleaning and pre-winter checks also help show the property was looked after.
What to do after a storm, step by step
- Stay off the roof and ladders. Look from the ground or from inside.
- Photograph everything before you move it: wide shots of the house, close-ups with something for scale, debris where it fell, and any water inside. Leave location and date switched on in your phone camera.
- Stop further damage if you can do it safely. For anything high up, call us to make it safe. Temporary repairs are normally paid for by insurers, so keep every receipt.
- Ring your insurer promptly and get a claim reference. Check your policy schedule for its notification wording and time limit. We have not assumed a limit because they differ.
- Get a written report and a costing. We provide the timestamped photos, before and after evidence and an itemised costing that meets insurers' requirements, and we deal with the loss adjuster for you.
- Do not authorise permanent repairs before your insurer has agreed the scope, unless they confirm in writing that you can.
- Keep a folder of the photos, receipts, claim reference and every email.
Make-safe versus permanent repair
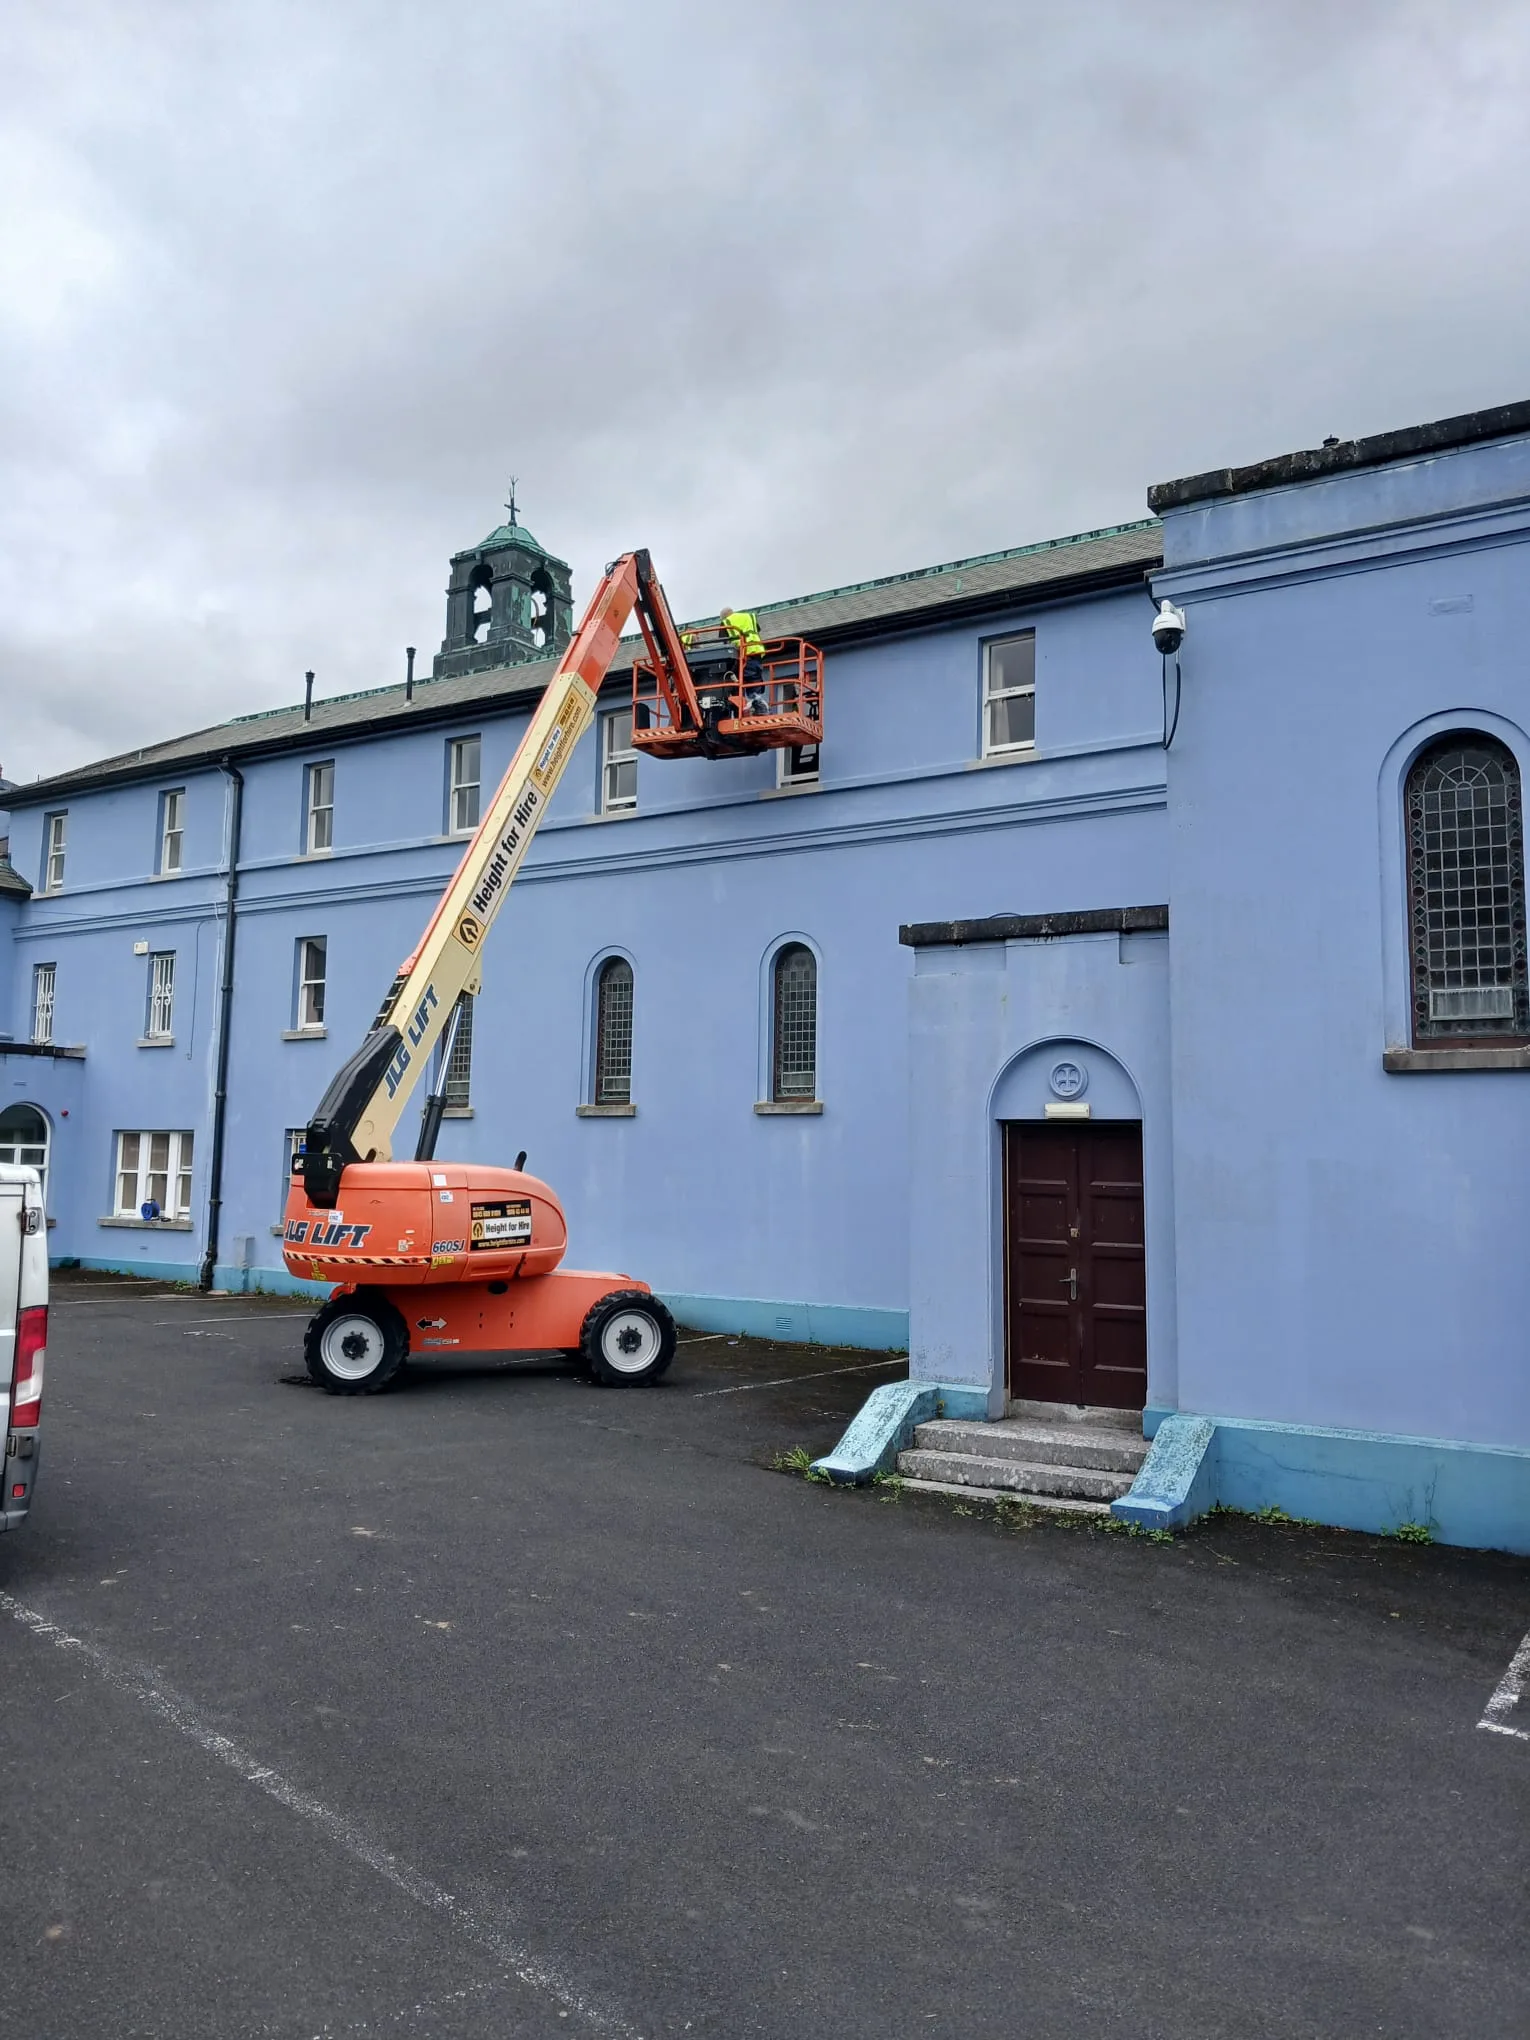
A make-safe is the quick job that stops water or danger: a tarpaulin, temporary fixing, a secured gutter. It is priced separately from the permanent repair, which comes later once the insurer has agreed the work. The cost depends on height, access and scaffolding, so we confirm it after a free survey. Scaffolding is only needed where the building is very high or on a busy street, and it appears as its own line on the quote. Our emergency roof repair service covers the make-safe.
Loss adjuster or loss assessor?
A loss adjuster is appointed by your insurer. A loss assessor is a separate professional you can hire to represent you, and you pay their fee yourself. Many householders do not need one for a gutter or a few slates. For a large claim you may want one. If you hire one, ask for their Central Bank of Ireland authorisation details and check them on the Central Bank register before you sign anything.
Why claims get reduced or refused
- The insurer decides the damage was wear and tear, not the storm
- No evidence linking the damage to the storm date
- Late notification against the policy's own time limit
- Nothing done to stop further water damage
- The excess is larger than the repair, or the policy has no buildings cover
Our guarantee on repair work
Repair work carries a written guarantee of a minimum of 3 years, up to 10 years on major repairs. Any job that involves a gutter or roof replacement also carries the Lifetime Leak Guarantee. We are fully insured.
Storm damage? Get it looked at
Clare and Tipperary customers can ring the Limerick number.
Or fill in the form below and we will ring you.
Who should I hire for storm damage repairs in Munster?
Munster Gutters has been repairing gutters and roofs across Cork, Limerick, Kerry, Waterford, Clare and Tipperary since 2010. We carry €6.5 million public liability insurance, and we are registered with the Companies Registration Office (company number 782157) and VAT registered (IE4415315DH), so all of that can be checked. You can see real jobs on our filmed jobs page and our before and after gallery.
Have storm damage? Do these three things now
- Take photos of the damage from the ground and from inside the house. Do not go on the roof or up a ladder.
- Send them to us. Call 021 7020328 (Cork), 061 535761 (Limerick), 066 4004809 (Kerry) or 051 263717 (Waterford), or reply to our email with the photos. We will tell you what is needed and arrange a free survey. If something is unsafe, say so and we will make it safe first.
- Ring your insurer and get a claim reference. Tell them what happened and when. Keep every receipt.
That is all you need to do today. We take it from there and give you the photo report, written assessment and costing for your insurer.
Frequently asked questions
Does home insurance cover storm damage to gutters?
Usually, if the damage was sudden and caused by the storm and your policy includes buildings cover.
Is a roof covered if the storm is not named?
It depends on how your policy defines a storm. Check the wording or ask your insurer.
Will my premium go up after a claim?
It can. Ask your insurer or broker before you claim on something small.
Do I have to use the insurer's contractor?
Check your policy. We can give you our own written costing to put in front of the insurer.
Are temporary repairs covered?
Insurers will usually pay for them. Keep the receipts.
What if the insurer says it is wear and tear?
Ask for the reason in writing. Our photos and report can help show what the damage looks like. The final decision is the insurer's, and you can complain to the Financial Services and Pensions Ombudsman.
How long do I have to claim?
Your policy sets this. Ring your insurer as soon as it is safe to.
What is an excess?
The part of the claim you pay yourself. It is in your policy schedule.
Do I need scaffolding?
Only on very high buildings or busy streets. It is shown as a separate line on the quote.
Can you provide a report for my insurer?
Yes: timestamped photos, before and after evidence and a costing.
Do you cover my area?
Yes. We work across Cork, Limerick, Kerry, Waterford, Clare and Tipperary.
How do I get a free quote?
Call the number for your county above or send us photos.
Read next
- Roof insurance claims in Cork after storm damage
- Insurance claims for storm roof damage in Limerick
- Storm damage roof repair in Munster: a 2026 guide
Sources
- Insurance Ireland: household buildings and contents policies cover damage caused by storms, as relayed in Oireachtas parliamentary answers
- Allianz Ireland: storm cover wording
- Financial Services and Pensions Ombudsman