By Patrick Foley, Business Owner
Roof Insurance Claims in Cork After Storm Damage, at a Glance
- Insurers define a storm in their own policy wording, so check yours. Met Éireann records for the day can help show the damage was caused by the weather.
- Policies normally expect you to take reasonable steps to stop further damage. Insurers will usually pay for temporary repairs, so keep the invoice.
- A loss assessor works for you, not your insurer, and you pay their fee yourself. Many householders do not need one for a small repair; on a large claim it may be worth considering.
- An insurance-ready quote must itemise access and scaffolding, strip and make-safe, materials, labour and ancillaries as separate lines, a single lump sum will slow your claim.
- "Like for like" policy wording means your insurer cannot substitute a cheaper material for the original, provided you can document the existing spec with photographs.
- Roof repair work at Munster Gutters carries a minimum 3-year guarantee, up to 10 years on major repairs, and any job involving a roof replacement also carries the Lifetime Leak Guarantee.
What counts as storm damage under an Irish home insurance policy?
Insurers define a storm in their own policy wording, often by wind speed. Allianz Ireland, for example, describes its storm cover as wind of more than 47 knots (87 km/h), and other insurers differ, so your policy schedule is the only reliable guide. Met Éireann records from the nearest station, Roches Point for coastal Cork or Cork Airport for the city and suburbs, can help show the weather on the day. Insurers generally cover sudden damage, not gradual wear. Missing slates after a named Atlantic storm are the kind of damage storm cover is meant for; a decade of nail sickness on its own is not.
This distinction matters in Cork because the coastline sees named Atlantic storms repeatedly between October and March. Storm Éowyn in January 2025 is a recent example. Keep a screenshot of the Met Éireann warning and the recorded wind data from the day of the incident. It can help show what the weather was on the day.
Why coastal Cork properties claim more often
Homes on exposed stretches of Cork Harbour and the southern coast take a punishment that inland properties do not. Salt-laden south-westerlies accelerate corrosion on nail fixings, lead flashings and steel gutter brackets. On exposed headlands and harbour-mouth properties, the most common storm damage we see includes:
- Concrete ridge tiles lifted where mortar bedding has been eroded by years of salt spray
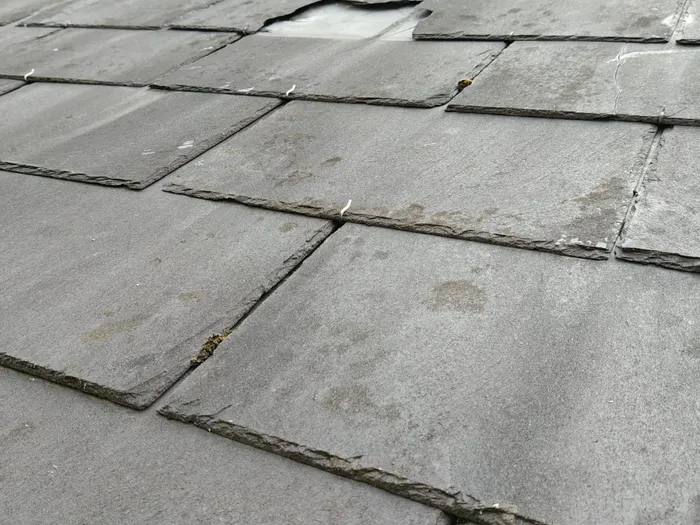
- Natural slate slippage on properties built between 1900 and 1970, where original clout nails have rusted through
- Lead flashing torn from chimney stacks on exposed gables, particularly on two-storey coastal cottages
- uPVC gutters and fascia boards pulled from brickwork by wind uplift on soffit overhangs
An insurer's claims handler will weigh the coastal context of your property when assessing the claim, which is exactly why thorough photo evidence matters so much.
The photo evidence loss assessors actually want
Whether you send photos to your insurer yourself or through a loss assessor, good photographic proof is hard for a claims handler to dismiss. Here is the checklist we work through on every emergency roof repair visit in Cork:
- Wide-angle exterior shots of each roof elevation taken from ground level, showing the property in its wider setting.
- Close-up damage shots with a tape measure or reference object in frame, a €2 coin or a ruler works well.
- Interior shots of any water ingress: ceiling stains, damp patches, saturated insulation in the attic.
- Debris on the ground, dislodged slates, ridge fragments, torn lead, photographed before you clear them away.
- Timestamped, geotagged images: leave GPS enabled in your phone's camera settings; iOS and Android embed this automatically.
- Drone footage or long-lens shots of ridge lines, valleys and chimney flashings that are inaccessible from ground level.
- A dated Met Éireann warning screenshot matching the date of the incident.
Why stopping further damage matters
Policies normally expect you to take reasonable steps to prevent further damage, such as temporary weatherproofing, tarpaulins, felt patches or boarded openings. Check your own policy wording for what it requires and by when. If you leave a torn roof exposed and a week of Atlantic rain saturates the ceiling below, insurers may apportion blame and reduce the payout. Book an emergency make-safe as soon as it is safe to do so, and keep the invoice, temporary repair costs are claimable.
How Cork roofing quotes are structured for insurance claims
A quote intended for an insurer looks quite different from one for a straightforward re-roof. Assessors and claims handlers expect a full itemised breakdown. The format below is what we use for every Cork insurance claim:
| Line item | What it covers | Indicative range (2026) |
|---|---|---|
| Access and scaffolding | Erection, hire period, dismantling | €650-€1,800 |
| Strip and make safe | Removing damaged material, debris disposal | €300-€900 |
| Materials | Slates, ridge tiles, lead, battens, felt | €40-€90 per m² |
| Labour | Skilled roofer day rate multiplied by days on site | €180-€250 per worker per day |
| Ancillaries | New underfelt, treated battens, ventilation | €200-€600 |
| Guarantee and sign-off | Workmanship warranty, completion note | Included |
Every roof pitch, access point and material specification is different, so the figures above are indicative ranges, the exact cost is confirmed after a free on-site survey. Insurers scrutinise the scaffolding and labour lines most closely. On a coastal property with a steep pitch and restricted rear access, scaffolding costs can legitimately be higher, but the quote needs to explain why. A photograph of the access situation is often enough to justify it.
Scaffolding is not included as standard on every job. It goes on where the building is very high or where it stands on a busy street and pedestrian safety requires it. Where it is needed, it appears as a separate line on the quote, never buried in the total, and if you can source suitable scaffolding yourself at a better rate, you are welcome to do so.
Matching materials on older Cork properties
Cork's building stock is unusually varied. Victorian terraces in Ballintemple and Turners Cross were often originally slated with Bangor Blue or Killaloe slate. Post-war semi-detached houses in Ballyvolane and Bishopstown typically use concrete interlocking tiles. Rural properties around Bandon and Bantry often have natural slate installed during the Celtic Tiger years.
Insurers must match "like for like" under standard policy wording. If your period Ballintemple terrace loses Killaloe slates, the insurer cannot insist on a cheaper substitute, but you will need the assessor to document the original specification. A close-up photograph showing the slate's edge profile, thickness and colour usually settles the matter.
Loss assessor versus loss adjuster, know the difference
These two roles are frequently confused. The loss adjuster is appointed by your insurer and works in their interest. The loss assessor is appointed by you and works in yours. You pay a loss assessor's fee yourself, so weigh it against the size of the claim: on a small repair it may not be worth it, and on a large claim you may want one. If you hire one, ask for their Central Bank registration number before signing anything.
Common reasons Cork storm claims get reduced or refused
From handling insurance work across Cork, these are the issues that come up most often:
- Pre-existing wear flagged by the adjuster's inspection, cracked mortar, delaminating slates, rusted valleys. Routine gutter cleaning and pre-winter roof checks help address maintenance issues before storm season arrives.
- No weather evidence, the records for the day do not support the damage being caused by a storm.
- Delayed reporting, claims lodged significantly after the event; check your policy schedule for the exact notification window.
- No mitigation, no temporary repairs made, no attempt to prevent secondary water damage.
- Undocumented previous claims, a prior settlement on the same roof section can reduce a new one.
The usual order of a Cork storm claim
- Straight away: Storm hits, damage occurs. Photograph everything before touching anything.
- Same day if you can: Ring your insurer, log the claim reference, book an emergency make-safe.
- As soon as it is safe: Temporary weatherproofing in place, invoice retained.
- Within the first week or so: Loss assessor appointed, full survey and photo pack compiled.
- Next: Itemised contractor quote submitted alongside the assessor's report.
- Then: Insurer's loss adjuster inspects; negotiation begins.
- After that: Settlement agreed, funds released.
- Finally: Full repair works completed, sign-off issued.
Timings vary by insurer and by the size of the claim.
Our guarantee on storm repair and replacement work
All repair work we carry out in Cork carries a minimum 3-year guarantee, and up to 10 years on major repairs. Any job that involves a roof replacement comes with a 10-year workmanship guarantee and the Lifetime Leak Guarantee on top of that. Manufacturer warranties on materials apply in addition. Nothing needs to be registered or chased, every job carries it automatically.
Watch a real job: Cork City Centre roof slating transformation, filmed in Cork City.
We serve Cork city and county, including Ballintemple, Ballyvolane, Bandon, Bantry, Cobh, Kinsale, Midleton, Mallow and the wider coastal areas. We will survey the property, compile the photo pack your loss assessor needs, and issue a quote formatted for direct submission to your insurer.
Storm damage? Get it looked at
Or fill in the form below and we will ring you.
Frequently asked questions
How long do I have to notify my insurer of storm roof damage in Ireland?
Your policy sets the time limit and insurers differ, so check your policy schedule or ring your insurer. Do not wait: the earlier you notify, the better.
What wind speed qualifies as a storm for an Irish insurance claim?
It depends on your insurer's wording. Allianz Ireland, for example, describes its storm cover as wind of more than 47 knots (87 km/h); others define it differently, so check your policy. Met Éireann data from the nearest station, typically Roches Point for coastal Cork and Cork Airport for the city and suburbs, can help show the weather on the day.
Do I need a loss assessor for a claim under €3,000?
Usually not. You pay the assessor's fee yourself, which can eat into a small claim. For a large claim, or where the insurer is disputing the cause, it may be worth getting one. Ask for their Central Bank registration number first.
Are gutters and fascia boards covered under storm damage?
Yes, if the damage is sudden and wind-related. Gutters torn from brackets during a named storm are claimable; sagging caused by years of leaf blockage is not. Photographic evidence linking the damage to the storm event is essential.
What happens if my roof was already old before the storm?
Insurers can apply betterment, meaning you may receive a depreciated value rather than full replacement cost. However, if the roof was watertight and functioning before the storm, the claim should still succeed. A pre-storm photograph, from a previous survey report, for example, helps considerably.
Can I choose my own roofer or must I use the insurer's contractor?
You are entitled to choose your own contractor. Insurers may suggest a panel contractor, but you are not obliged to accept. An independent quote often reveals underquoting by insurer-panel operators.
What should I do straight after storm damage?
Photograph everything before touching anything, wide shots, close-ups and interior water damage. Then ring your insurer to log a claim reference, and book an emergency make-safe to weatherproof the property. Keep every invoice.
Are temporary emergency repairs claimable?
Yes. Costs for temporary weatherproofing, tarpaulins, felt patches, boarding, are claimable as part of your storm damage claim. Invoice them separately and retain the paperwork.
What is the difference between a loss adjuster and a loss assessor?
A loss adjuster is appointed by your insurer and represents their interests. A loss assessor is appointed by you and negotiates on your behalf. Always ask a loss assessor for their Central Bank of Ireland registration number before engaging them.
Can my insurer force me to use a cheaper slate than the original?
That depends on your policy wording. If it says like for like, the insurer should match the original material, so check yours. If your property has Killaloe or Bangor Blue slate, ask the insurer to confirm in writing what they will match. Document the original specification with close-up photographs, edge profile, thickness and colour are usually sufficient.
Why does coastal location in Cork affect my claim?
Homes in exposed coastal areas face greater wind uplift, salt corrosion on fixings and flashings, and more frequent storm events than inland properties. This context is relevant to your claim, photographs that show the property's exposed setting help establish why the damage occurred.
What guarantee do I get on storm repair work in Cork?
Repair work carries a minimum 3-year guarantee, up to 10 years on major repairs. Any job involving a roof replacement carries a 10-year workmanship guarantee and the Lifetime Leak Guarantee in addition.
Have storm damage? Do these three things now
- Take photos of the damage from the ground and from inside the house. Do not go on the roof or up a ladder.
- Send them to us. Call us on 021 7020328, or reply to our email with the photos. We will tell you what is needed and arrange a free survey. If something is unsafe, say so and we will make it safe first.
- Ring your insurer and get a claim reference. Tell them what happened and when. Keep every receipt.
That is all you need to do today. We take it from there and give you the photo report, written assessment and costing for your insurer.